We are not an insurance company or an agent. Nothing on this page promises that your carrier will renew your policy, lower your rate, or accept a treated roof. Every carrier sets its own rules, and your agent is the one to ask.
Why carriers care about an older roof
Homeowners insurance in North Carolina has gotten tighter over the last few years. Premiums have climbed, and some carriers have pulled back on who they'll cover.
The roof is one of the first things underwriters look at. An old or worn roof is more likely to leak or fail in a storm, and storms drive a lot of claims. So as a roof ages, many carriers look at it harder. How hard depends on the company. Some ask for an inspection. Some want recent photos. Some set limits on coverage for roofs past a certain age.
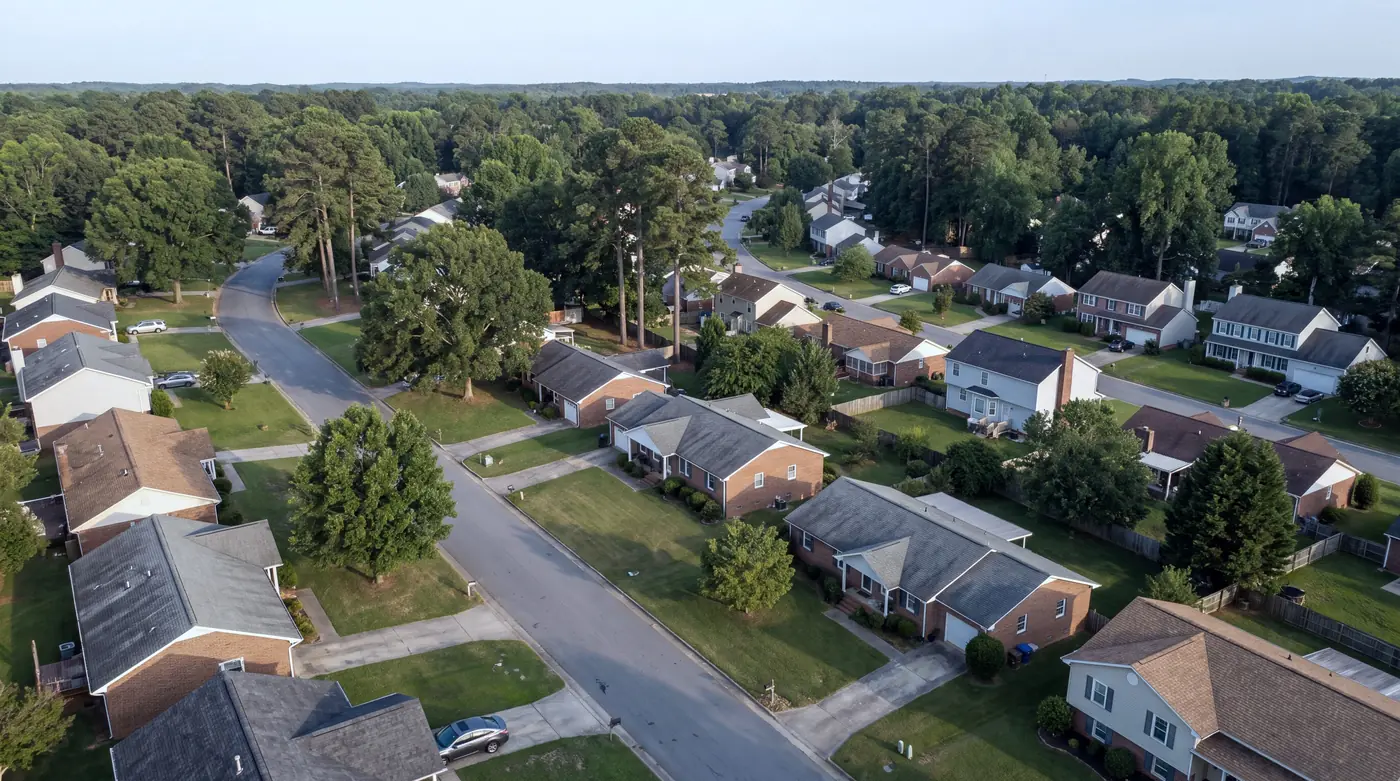
Some don't call at all. They look at aerial or satellite photos of your roof. In 2024, The News & Observer reported on a Boone homeowner whose carrier decided not to renew his policy based on aerial photos. The photos showed discoloration and streaking on the roof. He had a local roofer put in writing that it posed no risk, and he ended up finding coverage with another company.
Your roof's condition is on record whether you know it or not. It pays to know what it looks like from above.
What carriers and agents may ask about
Every carrier is different, but these come up a lot:
- Roof age. Usually the year the roof was put on. Dig out your records if you have them.
- Roof type. Asphalt shingle, metal, tile and so on.
- Visible condition. Missing or curled shingles, granule loss, black streaks, debris and moss.
- Signs of damage. Hail hits, storm damage, sagging.
- Maintenance records. Proof that someone has kept up with the roof.
If a letter comes asking about your roof, read it closely. It will usually say what the carrier wants and by when. Call your agent right away. Waiting until the week before renewal leaves you very few options.
Also ask how your policy pays on the roof. Some policies pay a depreciated value on an older roof instead of the full cost to replace it. Your agent can tell you which kind you have.
Where a tune-up and treatment can help
Some roofs get flagged for wear that can be fixed. Loose shingles. A tired seal at the chimney. Dry, faded shingles shedding grit into the gutters. Those are the problems a tune-up and treatment go after.
Here's how it can help:
- Small defects get fixed. The tune-up secures lifted shingles, fixes nail pops and reseals flashing. Those are things an inspector may write down.
- The shingles get treated. APEX-1132 is a soy-based treatment made to slow the aging of asphalt shingles. In lab testing it improved granule adhesion and helped shingles pass a pliability test at 55°F. The lab results page walks through the numbers.
- Ask for a record. Ask us for a written record of the work for your insurance agent. Each treatment also comes with a 5-year transferable warranty, and we give you the written terms before work starts.
That record is something you can hand to your agent. Whether it changes anything is the carrier's call.
When this can help, and when it won't
It can help when
- The roof is aging but still sound, with solid decking
- The concern is wear like dry shingles, granule loss or small defects
- Your carrier gives weight to repairs and maintenance records
- You have time before the renewal date to get the work done
- Your agent has told you what they need to see
It won't help when
- The carrier has a firm roof age cutoff that paperwork can't change
- The roof has hail or storm damage that belongs in a claim
- Shingles are missing, broken or curled hard across the roof
- Leaks are coming from rotted decking
- The roof is metal, tile, slate or flat
What to do if your carrier flags your roof
- 01Call your agent
Ask exactly what the carrier needs. An inspection, photos, a repair, or proof of a new roof. Ask for the deadline in writing.
- 02Get the roof looked at
Book a free roof assessment. The owner checks whether the roof is a candidate for treatment or truly needs replacing.
- 03Fix what can be fixed
If it's a candidate, the tune-up and treatment usually fit into one afternoon on a typical house.
- 04Send the records
Ask us for a written record of the work. Give it to your agent and ask them to pass it to the carrier.
- 05Shop if you have to
If your carrier won't budge, an independent agent can check other companies. Not every carrier judges roofs the same way.
If the roof really is done
Sometimes the honest answer is that the roof needs replacing. If we find soft decking, cracking across most of the roof, or shingles worn down to bare asphalt, we'll say so. A treatment on that roof wastes your money, and it isn't likely to change an insurer's mind.
We don't sell new roofs, so we have no stake in which way you go. Our side-by-side on rejuvenation vs. replacement can help you weigh it, and the free roof assessment will tell you where your roof stands.
Common questions
Can my insurance company drop me because my roof is old?
Carriers in North Carolina set their own underwriting rules, and roof age and condition are common factors. Some do decline to renew over a roof. Any notice you get should state the reason. Talk to your agent first. If you think a decision is wrong, the NC Department of Insurance takes consumer questions and complaints.
Will a roof rejuvenation treatment make my roof insurable?
No one can promise that, us included. A tune-up and treatment can help a sound, aging roof look and perform better, and you can ask us for a written record of the work. Whether your carrier accepts that is up to them. Ask your agent before you book.
What does an insurance company want to see on an older roof?
It depends on the carrier. Common asks are the roof's age, recent photos, an inspection, or proof of repairs. Some want to see that specific problems were fixed, like missing shingles or worn flashing. Your agent can get you the carrier's exact list.
Does homeowners insurance cover an old roof that leaks?
Policies are generally written for sudden damage, like a fallen tree or hail. Leaks from age and wear are usually not covered. Read your policy or ask your agent to be sure.
Should I talk to my agent before getting the treatment?
Yes. Ask what records would help, then tell us at your assessment so you know what to ask for. If your agent says only a new roof will do, asking first saved you money.